GST Rates 2026: Old vs New Comparison & Key Changes
This guide explains how to compare previous GST rate schedules with any newly announced GST rates and what the key implications are for businesses and consumers. You will learn how to read and interpret rate changes, which business functions are most affected, how to assess impact on pricing and margins, and the practical compliance steps to take when rates are revised. The content is intended for business owners, finance teams, tax professionals and procurement managers who need a clear, actionable framework to prepare for GST rate revisions without relying on partisan commentary. Understanding the mechanics behind a rate change matters because it affects invoicing, input tax credit treatment, product pricing, cashflow and customer communication. Even when specific rate numbers are not at hand, a systematic approach helps organisations adapt faster and reduce compliance risk.
How to read an old vs new GST rate notification
When a tax authority issues a revised GST schedule, the official notification will typically list goods and services alongside their revised classifications and applicable rates. Start by obtaining the primary source (the official gazette or tax department website) rather than relying on secondary summaries. Focus on the scope language used in the notification, headings, exclusions, conditioned exemptions, and any explanatory notes are often decisive in determining how items are taxed.
Next, map each product or service in your catalogue to the line items in the notification. Pay attention to product descriptions and any classification rules; superficially similar products can be treated differently depending on definitions and packaging/branding conditions. Where the notification amends rate slabs or introduces new categories, note whether the change is absolute or conditional (for example, limited to certain pack sizes or specified sub-classes).
Business functions most affected by GST rate revisions
Pricing and procurement are usually the first business functions to feel the effect of a GST rate change. Procurement needs to review supplier prices and input tax credit availability; pricing teams must rework retail and channel prices to maintain margins or pass benefits to customers. Coordination between procurement, sales and finance is essential to ensure consistent treatment across purchase orders, sales contracts and promotional pricing.
Compliance and accounting teams must also update tax codes and accounting entries. System configurations for invoicing, e-way bills and returns depend on accurate tax mappings. Inadequate or delayed updates can result in incorrect tax collection or credit claims, leading to reconciliations, customer disputes and potential interest or penalties. A controlled change management process mitigates these operational risks.
Operational checklist after a GST rate change
Begin with an impact assessment: classify SKUs and services into affected and unaffected groups, estimate margin and cashflow effects, and identify contracts with price escalation or tax pass-through clauses. Use this assessment to prioritise system updates, stock valuation adjustments and supplier communications.
Then update IT systems and templates: implement revised tax codes in ERP and billing systems, change pricing and master data where needed, and update tax calculation rules for online stores and payment gateways. Prepare revised invoice templates and customer-facing tax breakdowns. Finally, plan for return filing and reconciliation, ensure that the accounting team understands any transitional guidance on credit utilisation or retrospective corrections.
Commercial and customer-facing considerations
Decide early whether to absorb, pass on, or partially pass on the change to customers. This decision affects competitiveness, demand, and margin. Clearly document the rationale for pricing changes and prepare communications for customers, distributors and retailers that explain the timing and extent of any price adjustments in plain language.
Also consider contract clauses and ongoing orders: long-term supply agreements and subscriptions often contain tax clauses that dictate how rate changes are handled. Review those contracts and, where necessary, negotiate amendments or provide formal notices. For consumer-facing businesses, update labels, promotions and checkout calculations to prevent disputes at the point of sale.
Managing input tax credits and stock on hand
When rates change, the GST credit available on existing inventory and on inputs used in production can be affected. Accounting teams should calculate the value of GST charged on stock and inputs and determine the correct treatment under transitional provisions, if any. Proper tagging of opening stock and purchases helps ensure the right tax credit is claimed in subsequent returns.
For manufacturers and retailers, re-costing of inventory to reflect new tax incidence is important for accurate profitability analysis and tax reporting. Maintain clear records of purchase invoices, tax paid and the dates of acquisition to support any retrospective claims or adjustments that may be allowed by authorities.
How tax advisors and internal teams should prepare
Tax advisors should provide a focused advisory note that maps company products and services to the new tariff schedule, outlines likely cashflow and compliance impacts, and recommends immediate technical and commercial actions. This note should include a prioritized action list for IT updates, reporting changes and customer communications.
Internal training is equally important: conduct targeted sessions for sales, customer care and finance so staff can answer queries and implement changes consistently. Establish a cross-functional transition team and a single source of truth for updated rates to avoid duplication and confusion during implementation.
Rate revisions in GST can have broad operational, commercial and compliance consequences. A structured approach, verify official notifications, map your catalog, update systems, re-price thoughtfully and communicate clearly, helps reduce disruption. Preparing early, coordinating across functions, and documenting decisions will make the transition smoother and minimise risk.
Frequently asked questions
What are the main changes in GST rates introduced in 2026 compared to the old structure?
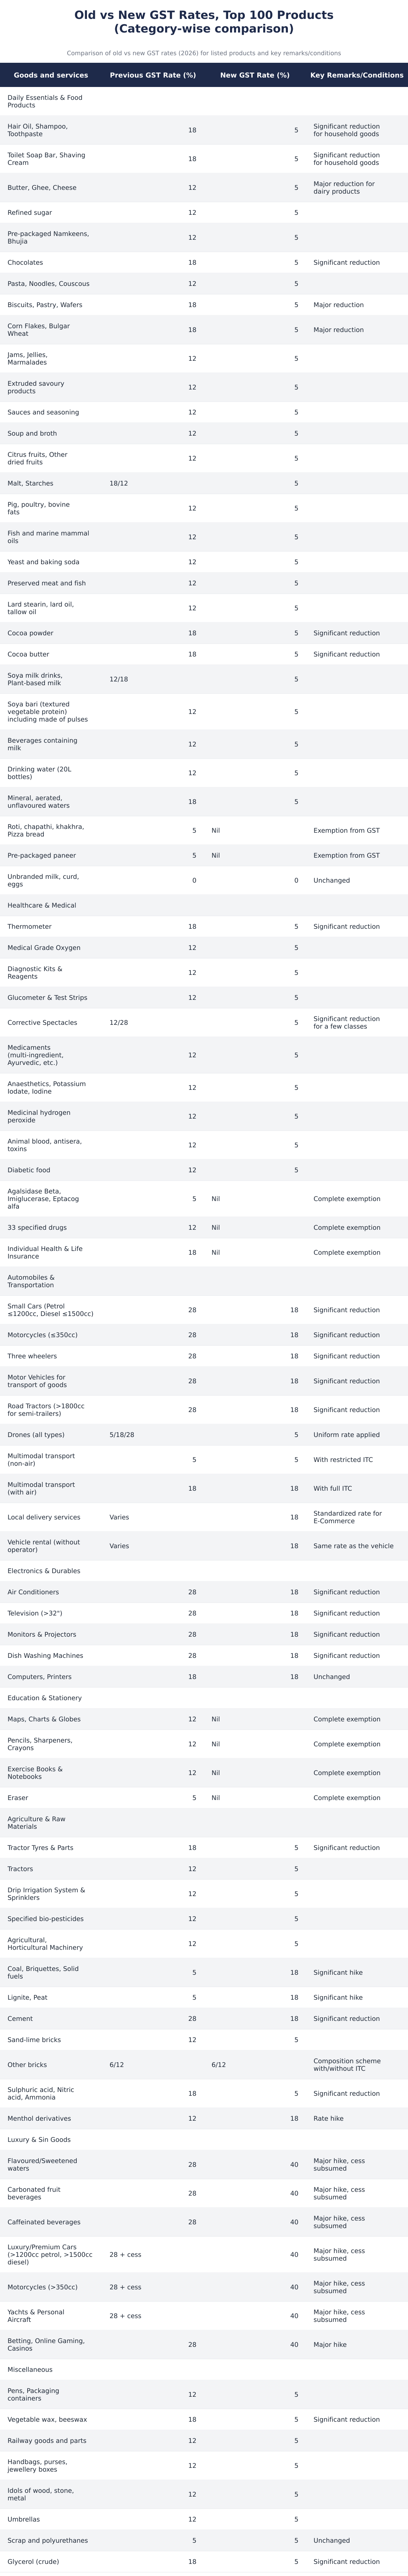
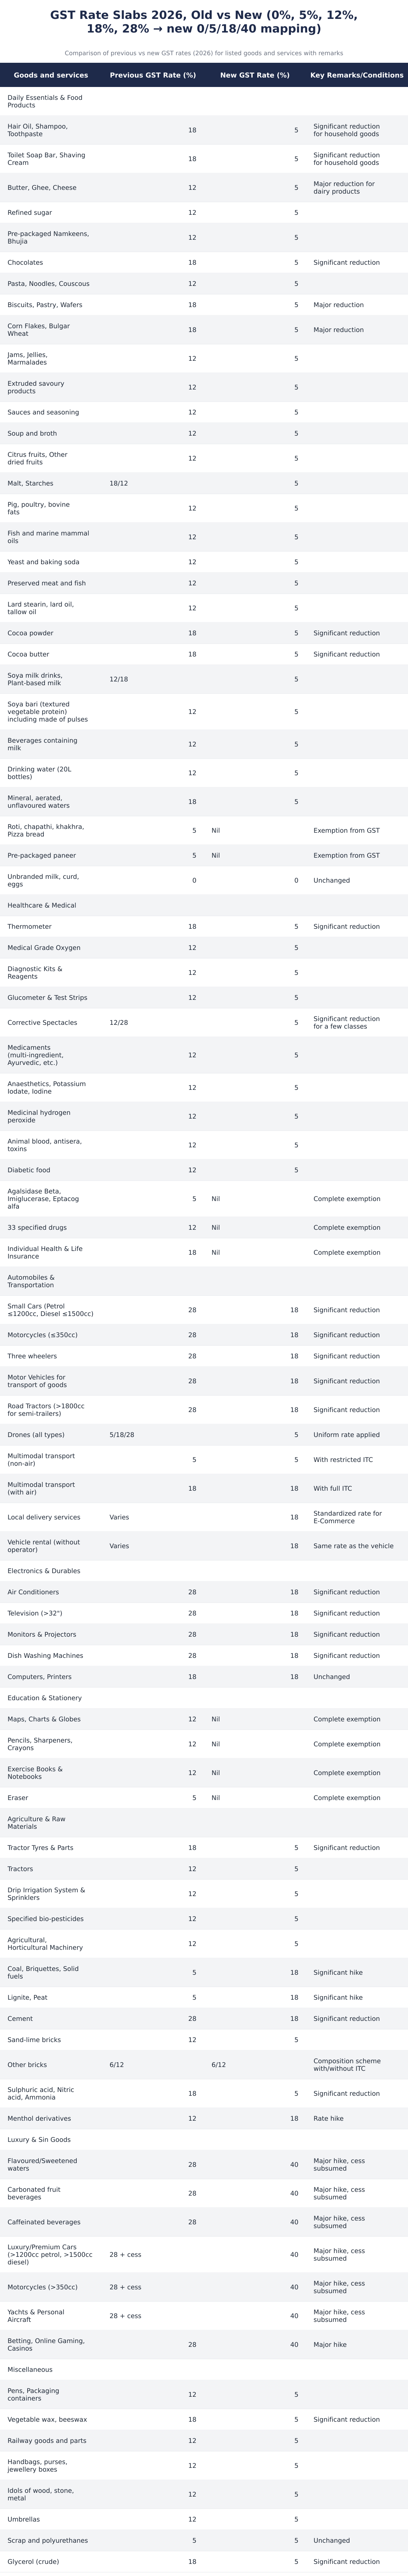
The 2026 GST revision simplifies slabs and reallocates many items, introducing a new demerit 40% rate while moving many everyday items to 5% or nil and most goods to a standard 18% rate. Before 22nd September 2025 the five-slab system included 0%, 5%, 12%, 18% and 28%; after the change essentials and merit goods were largely shifted to 5% or nil, standard goods stayed at 18%, and a new 40% flat rate targets tobacco, high-sugar and caffeinated drinks and luxury vehicles. Several previously 18% and 12% items (like many household food products, cosmetics, and medical devices) were cut to 5% or made exempt, while luxury and “sin” goods saw steep hikes. The revision also subsumed some cesses into the higher 40% rate for certain products and standardized rates for e-commerce and transport services in many cases.
When did the new GST rates take effect and which date marks the transition?
The new GST rates took effect after 22nd September 2025, with that date marking the transition from the old slabs to the revised structure. Items taxed under the pre-22nd-September-2025 slabs (0%, 5%, 12%, 18%, 28%) were reassessed and re-categorized into the post-change bands such as nil, 5%, 18%, and the new 40% demerit rate. For compliance, invoices and filings should reflect the new rates for supplies made on or after 23rd September 2025, and any specific transitional instructions issued by tax authorities must be followed. Some items retained unchanged rates (for example, unbranded milk and curd at 0% and certain items remaining at 18% or 5%).
Which everyday food and household items saw the biggest GST rate reductions in 2026?
Many packaged food and household items were moved from 12% or 18% down to 5%, and some staples became nil-rated; examples include butter, ghee and cheese (from 12% to 5%), biscuits and corn flakes (from 18% to 5%), and pre-packaged paneer and certain breads (moved to nil). Unbranded milk, curd and eggs remained unchanged at 0% while items like drinking water (20L bottles) fell from 12% to 5% and mineral/aerated unflavoured waters dropped from 18% to 5%. These cuts were aimed at reducing cost pressures on daily essentials, but packaged snack lines and certain processed foods were specifically listed for the lower rate. Note that some products with mixed prior rates (e.g., soya milk at 12/18%) were consolidated to 5% under the new structure.
Which items became fully exempt (nil GST) under the 2026 revision?
Several educational and basic food items were made completely exempt (nil GST), such as maps, charts & globes; pencils, sharpeners, crayons; exercise books and notebooks; erasers; pre-packaged paneer and certain breads like roti and chapathi. Additionally, 33 specified drugs and certain high-priority medicines and some life & individual health insurance products moved to nil, reflecting policy priorities for education, health and basic nutrition. Exempt status means no GST is charged on supply and suppliers cannot claim input tax credit on inputs used to provide these exempt supplies, so businesses should adjust pricing and input credit accounting accordingly. Check specific HSN classifications and official notifications to confirm product-level exemptions.
Which products were reclassified as ‘luxury’ or ‘sin’ goods and what are their new rates?
Several items were reclassified into the higher ‘luxury’ or ‘sin’ category and taxed at a new 40% demerit rate, including flavoured/sweetened waters, carbonated fruit beverages, caffeinated beverages, luxury/premium cars (subsuming previous cess), high-displacement motorcycles, yachts, personal aircraft and activities like betting, online gaming and casinos. Previously these items were in the 28% slab often with an additional cess; the 2026 change both raised the base rate and subsumed cesses into a single 40% rate for targeted demerit taxation. The measure aims to discourage consumption of high-sugar/caffeine drinks and luxury petrol/diesel vehicles while simplifying the tax structure by eliminating separate cesses on these items. Businesses supplying these goods should update pricing and GST returns to reflect the 40% rate and note that input tax credit rules may be restricted for demerit items in some cases.
How were GST rates for automobiles and transport changed in 2026?
Automobiles and many transport categories saw significant reclassification, with small cars (petrol ≤1200cc, diesel ≤1500cc), motorcycles ≤350cc, three-wheelers, goods vehicles and road tractors moved from 28% to 18%, while luxury/premium cars and large motorcycles were moved to 40%. The shift reduced GST on most mass-market vehicles and commercial transport, lowering the direct tax burden on everyday vehicles, but left higher-end personal vehicles subject to the steep 40% demerit rate. Multimodal transport services received differentiated treatment: non-air multimodal transport stays at 5% with restricted input tax credit, whereas multimodal transport involving air remains at 18% with full ITC. Vehicle rental services without operator were standardized to 18%, matching the rate applicable to the vehicle class.
What major changes affected healthcare, diagnostics and medicinal products under the new GST rates?
Healthcare saw broad rate reductions and targeted exemptions: many medical devices and diagnostics (thermometers, glucometers, diagnostic kits) moved from 12% or 18% to 5%, several named drugs and 33 specified medicines were fully exempt (nil), and select high-priority biologics like Agalsidase Beta and Imiglucerase were made nil. The policy reduces cost of essential medicines and diagnostic services while maintaining low rates for many medical consumables; remedial items like corrective spectacles were consolidated to 5% from prior mixed rates (12/28) for certain classes. Suppliers and hospitals should note that exemption (nil) eliminates GST collection but also disallows input tax credit on inputs for those exempt supplies, affecting procurement accounting.
How did the 2026 GST changes affect agriculture, raw materials and inputs for farmers?
Key agricultural inputs and machinery were mostly reduced to 5% from higher rates: tractors and tractor tyres fell to 5% (from 12% and 18% respectively), drip irrigation systems and specified bio-pesticides moved from 12% to 5%, and many horticultural/agricultural machinery items were cut to 5% to support farm productivity. However, some fuel-related and solid fuel items like coal and lignite were hiked from 5% to 18%, representing a targeted increase in certain raw fuel categories. The reductions lower the upfront cost of farm equipment and irrigation systems, but farmers and agri-suppliers should check composition scheme rules and input tax credit availability for specific items and HSN codes.
Will input tax credit (ITC) availability change under the new GST 2026 rates and how should businesses adjust?
Yes, ITC availability changes for some categories: exempt (nil) supplies, such as certain educational stationery and specified drugs, mean suppliers cannot claim ITC on inputs used for those supplies, while some service and transport categories have restricted ITC (for example non-air multimodal transport at 5% with restricted ITC). For demerit items taxed at 40%, ITC treatment may be limited or subject to specific rules, and businesses should carefully map old ITC claims to the new rate structure to avoid disallowances. Companies should update ERP/GST configuration to new HSN-rate mappings, reclassify products in invoices, and consult official notifications to adjust transitional ITC accounting and stock handling at the effective date. It’s prudent to perform an ITC impact assessment for affected SKUs and review procurement contracts and pricing to reflect both tax and credit changes.
Need help staying GST compliant?
MoneyGence's AI Finance OS tracks your compliance, wallet share, and finances in one place, built for agencies and growing businesses.
Get started with MoneyGence